In short
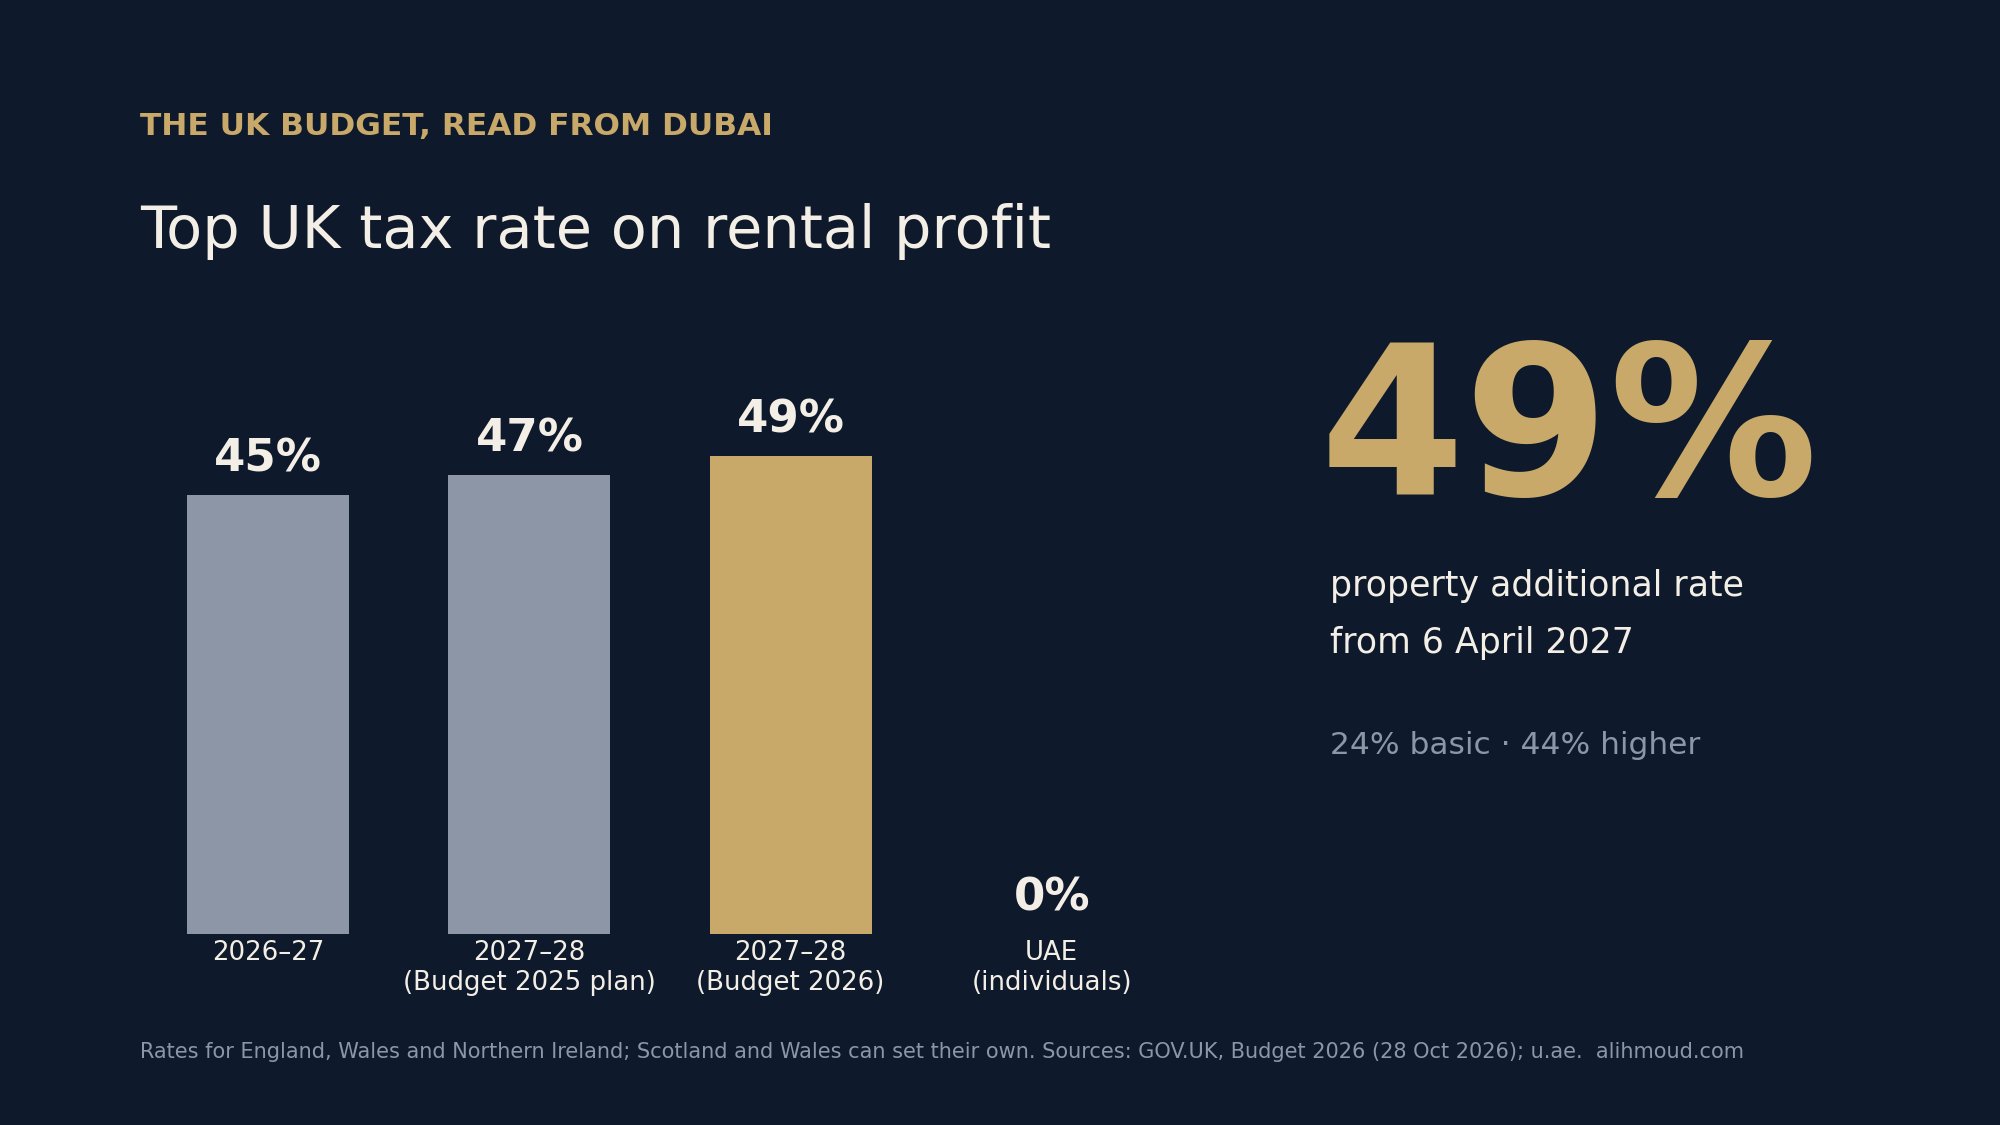
- From 6 April 2027, UK rental profit is taxed at 24%, 44% or 49%, four points above the main rates. Living in Dubai does not take UK rent out of UK tax.
- From 1 April 2028, owners of homes in England valued at £2 million or more pay a new surcharge of £2,500 to £7,500 a year.
- Five dates now belong in the diary of anyone who owns in London and lives, or plans to live, in Dubai.
Since the Budget on 28 October, a question clients often ask me is a short one: should I sell London? It is the wrong first question. The right one is what the London home will cost to keep from April 2027, after tax, and whether that still makes sense next to the life you are building here. The Budget has made that number easier to work out, because most of the changes that matter to a London owner now have a date attached.
What changed, and why it reaches Dubai
Budget 2025 had already created separate tax rates for property income: 22%, 42% and 47% from April 2027. Budget 2026 adds a further two points. HMRC's policy paper of 29 October 2026 confirms rates of 24% (property basic), 44% (property higher) and 49% (property additional and trust rate) for the 2027 to 2028 tax year onwards. The same 24/44/49 applies to savings interest. These property rates apply to individuals in England, Wales and Northern Ireland; the Scottish and Welsh governments have been given the power to set their own.
The part people miss is residence. GOV.UK is plain that living abroad does not remove UK tax on UK rental income. Under the Non-Resident Landlord Scheme, your letting agent or tenant deducts basic rate tax from the rent unless HMRC has approved you to receive it gross, and you still declare it on a Self Assessment return. The UAE, by contrast, does not levy income tax on individuals (u.ae), and the Ministry of Finance has said an individual's personal real estate investment income is outside Corporate Tax where no licence is needed. So the move changes where you live. It does not change where London rent is taxed.
The five changes, with dates
| Change | What it means | From |
|---|---|---|
| Property income rates | 24% / 44% / 49% on UK rental profit | 6 Apr 2027 |
| Savings income rates | 24% / 44% / 49% on taxable UK interest | 6 Apr 2027 |
| High Value Council Tax Surcharge | £2,500–£7,500 a year, homes in England worth £2m+ | 1 Apr 2028 |
| Property income reporting | Consultation on letting agents and deposit schemes reporting to HMRC | Closes 20 Jan 2027 |
| Selling while non-resident | Late-filing penalties stop once the sale is reported and paid through Self Assessment | 28 Oct 2026 |
The surcharge has four bands, set by a Valuation Office exercise: £2,500 a year from £2m to £2.5m, £3,500 to £3.5m, £5,000 to £5m and £7,500 above £5m. It falls on owners, is collected with council tax, and comes with a deferral option until the property changes hands. GOV.UK does not yet say how it treats owners who live abroad, so I would assume it applies until told otherwise.
The fifth change is a softening, not a new cost, and it sits beside a rule that has not changed: a non-resident who sells UK residential property must still report it within 60 days of completion, even with no tax to pay or a loss.
A worked example
Take a London flat producing £80,000 a year of rental profit, all of which sits in its owner's higher band. In 2026 to 2027 the tax at 40% is £32,000. From April 2027, at 44%, it is £35,200: £3,200 more a year for the same flat and the same tenant. If the profit sits in the additional band, the rate goes from 45% to 49%, or £4,000 more on every £100,000. If the flat is in England and valued between £3.5m and £5m, add £5,000 a year from April 2028.
None of that is a reason to sell on its own. It is a reason to put a 2027 number next to the gross yield you quote yourself. For the Dubai side of the same comparison, my Rental Index tracks rents at One at Palm and The Lana month by month, and the real cost of buying a prime home here sets out the one-off fees. Past rents do not guarantee future income in either city.
What I would do
- Rerun the London yield at 44% or 49%, net of agent fees and finance costs, before deciding anything.
- Check the £2 million line. If your English home could be valued near it, budget £2,500 to £7,500 a year from April 2028 and watch for the Valuation Office exercise.
- Put 20 January 2027 in the diary if you let through an agent: that is when the reporting consultation closes.
- If you sell while living here, report within 60 days of completion, whether or not tax is due.
- Take your residence position to a UK adviser before you move money. What HMRC can still reach depends on your own facts, not on a postcode.
This is not tax or legal advice; take it to your adviser. If it raises a question about where Dubai fits in your plans, I explored the wider picture in where the next generation of wealth is moving.
If you are weighing a London home against a home here and would like the Dubai side done properly, send me a private enquiry.
Sources, all opened 12 November 2026: HM Treasury, Budget 2026 (28 October 2026); HMRC, Income Tax: changes to tax rates for property and savings income (29 October 2026); HMRC, Budget 2026 overview of tax legislation and rates, Annex A; HMRC, High Value Council Tax Surcharge on residential properties (28 October 2026, updated 4 November 2026); HMRC, Capital Gains Tax: returns for disposals of UK land and late filing penalties (28 October 2026); HMRC consultation, Improving Property Income Data Reporting (28 October 2026, closes 20 January 2027); GOV.UK, Tax on your UK income if you live abroad: rental income; GOV.UK, Tell HMRC about Capital Gains Tax on UK property or land if you're not a UK resident (updated 13 January 2026); u.ae, Taxation; UAE Ministry of Finance, Cabinet Decision on natural persons (May 2023). The worked example is illustrative arithmetic on marginal rates only; personal allowances, reliefs and Scottish or Welsh rates can change the result. This is not tax, legal or investment advice.