In short
- Knight Frank counted 86 Dubai home sales above $10M in Q3 2026, in the same quarter that prime prices dipped 5%, their first fall since 2020.
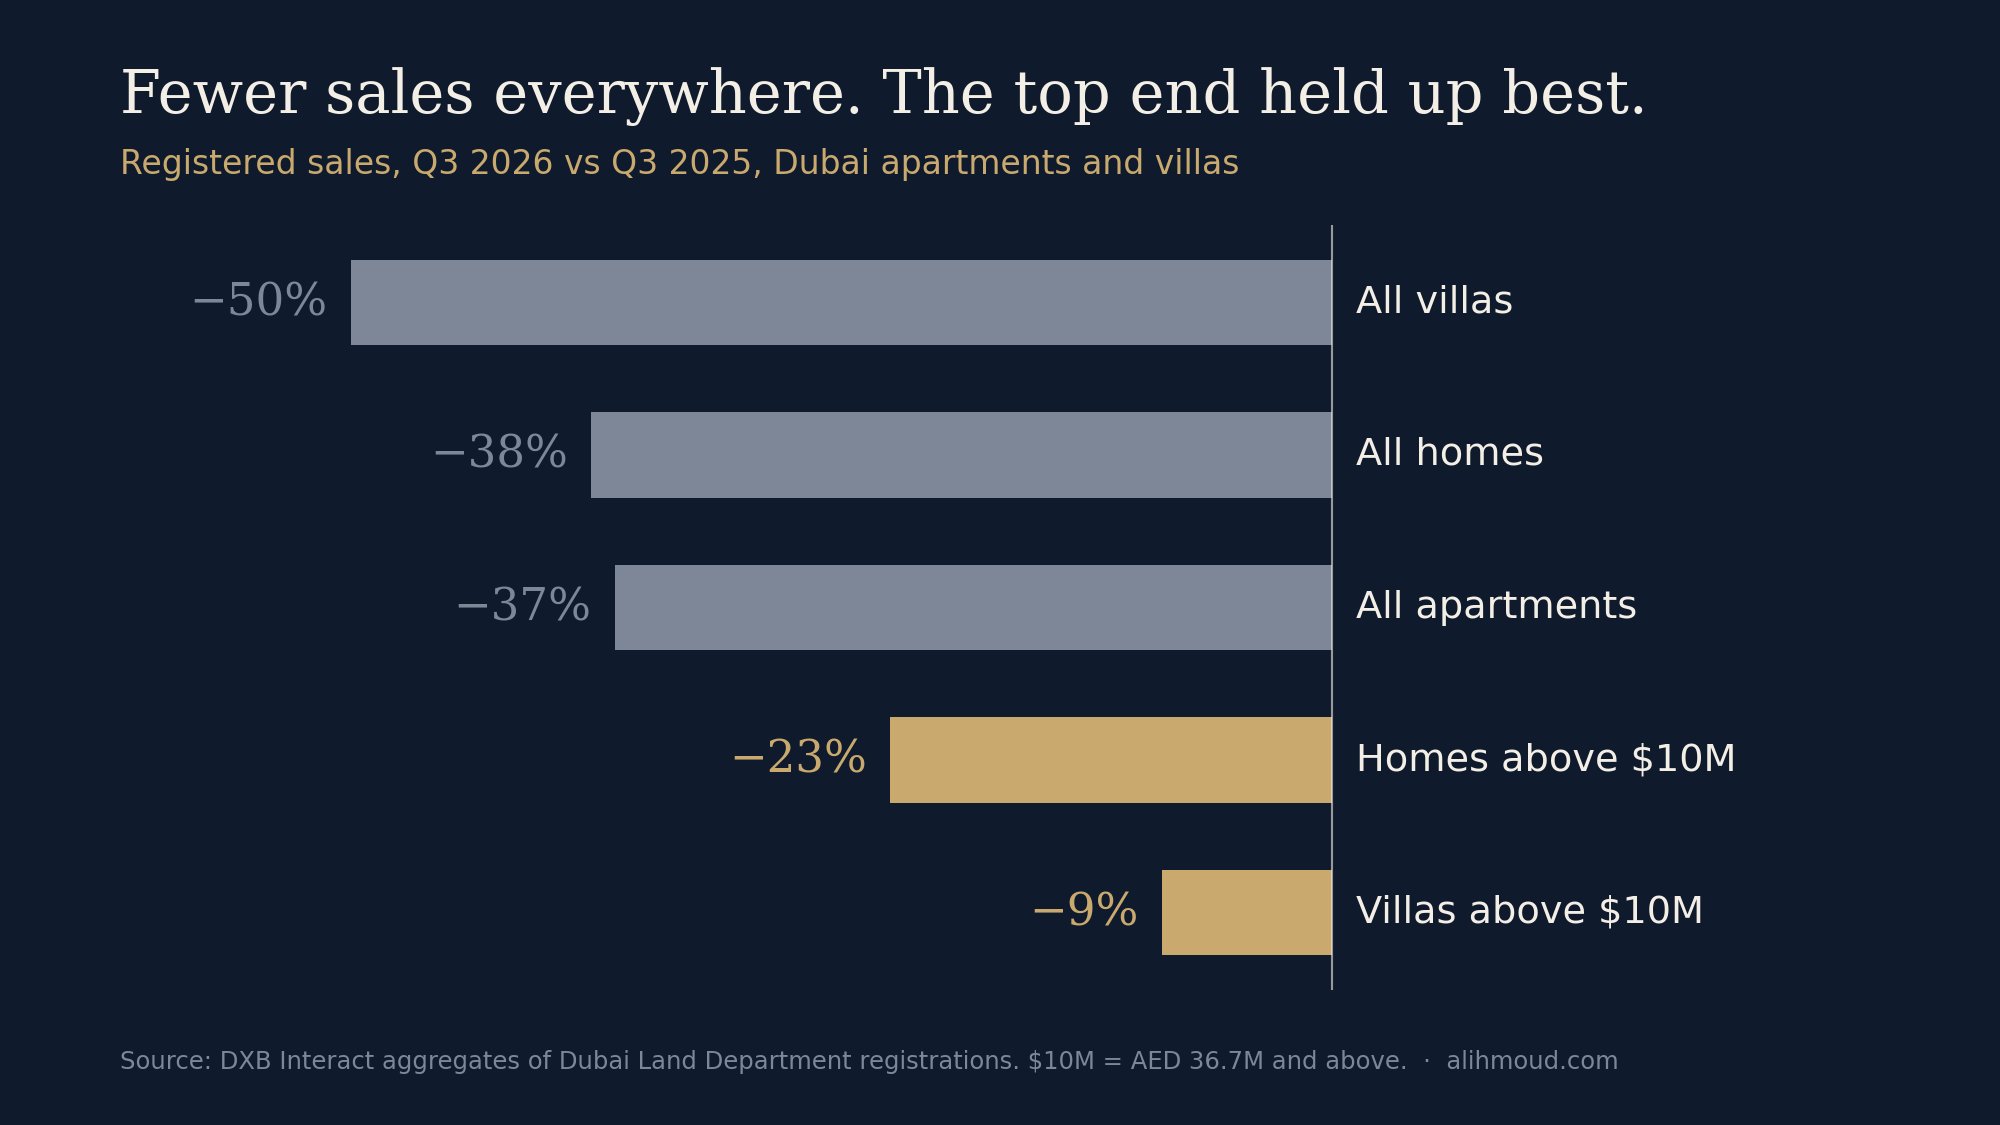
- In registered data, Dubai's apartment and villa sales fell 38% year on year in Q3. Sales at AED 36.7M and above fell 23%, and villas at that level only 9%.
- An index tells you what comparable homes fetch; a deal count tells you whether the buyers are still there. Read both before you decide anything.
Two headlines landed in the same week in October. Knight Frank's third-quarter research, reported by The National on 21 October 2026, said prices across Dubai's ten prime neighbourhoods fell 5% between the second and third quarters, the first dip since 2020. The same report counted 86 homes sold above $10 million. A question clients often ask me is which of the two to believe. My answer is both, because they measure different things.
Why an index can fall while the top end keeps trading
A prime price index tracks what comparable homes in a fixed set of neighbourhoods are worth. A count of $10 million sales tells you something else: whether the wealthiest buyers are still signing. Knight Frank's 86 is 17% fewer than a year earlier and about 34% fewer than in the second quarter, but its nine-month total of 412 is 15% ahead of the same period last year. Palm Jumeirah took 27 of the 86, even as Knight Frank put the island at AED 4,083 per sq ft, 9.1% lower over twelve months. The pace slowed. The buyers did not leave.
Registered medians can tell a different story again, as I showed in what Palm Jumeirah's Q3 registered sales really show. Different measures, different jobs.
The number I checked: who lost the most sales
I ran the same question through our own analysis of Dubai Land Department registrations: how did the top end fare against the rest of the market?
| Registered sales | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| All villas | 4,831 | 2,405 | −50% |
| All apartments | 49,470 | 31,313 | −37% |
| All homes | 54,301 | 33,718 | −38% |
| Homes AED 36.7M+ | 93 | 72 | −23% |
| Villas AED 36.7M+ | 46 | 42 | −9% |
A year ago, one registered home sale in 584 was above $10 million. This quarter it was one in 468. The resilience is a villa story: apartments at that level fell from 47 sales to 30. Our count of 72 is not Knight Frank's 86, because the thresholds, property types and data cuts differ, so compare each source with itself, never one with the other.
The three signals I watch
- Relative volume. Is the top end losing sales more slowly than the market? In Q3, clearly yes.
- The index for price direction. Villas above AED 36.7M registered a median of AED 4,240 per sq ft in Q3, against AED 3,990 in Q2. With 42 sales, which homes happened to sell moves that figure more than pricing does. For like-for-like direction, Knight Frank's 5% dip is the better guide.
- The next month. Early October registrations show 29 home sales at AED 36.7M and above, against a Q3 average of 24 a month. October is provisional, only four of those were apartments, and one month is not a trend.
What I would do
My rule is simple. When the index falls and the top-end count holds, negotiate on price, not on whether to buy. When both fall together for two quarters running, slow down and look again.
- Buying: the softer index is your room to negotiate; the steady deal count is why I would not expect distressed sellers. Ask for recent registered comparables in the building, not the headline.
- Selling: price against this quarter's evidence, not last year's peak. Buyers at this level are active, and they arrive with data.
- Holding: check what your home would earn while you wait, using the rental index, and read resale or off-plan on the Palm before switching.
If you would like the registered comparables for a specific home, send me a private enquiry and I will pull them for you.
Sources: Knight Frank Q3 2026 Dubai residential research, as reported by The National, "Dubai records strong sales for homes valued at over $10m", 21 October 2026 (86 sales above $10M; 412 year to date; prime-neighbourhood prices down 5% quarter on quarter; Palm Jumeirah AED 4,083 per sq ft, down 9.1% over twelve months). Our figures: DXB Interact aggregates of Dubai Land Department registered sales, apartments and villas, 1 July to 30 September 2026 against 1 July to 30 September 2025 and 1 April to 30 June 2026; $10M taken as AED 36.725M and above; October 2026 figures are provisional, pulled 9 November 2026, and the apartment figure is below ten sales. Medians are shaped by the mix of homes sold. Past prices and volumes are no guide to future ones; nothing here is a valuation or investment advice.