In short
- Dubai's branded homes carry a 56% average premium, well above the 30–35% seen globally (Morgan's International Realty, H1 2026). Two-thirds of those homes are still under construction, so most of that premium has never been tested.
- One at Palm is a building where it has been tested. From launch to handover and on to today, its price per sq ft has stayed at roughly 2.3 to 3.2 times the Palm Jumeirah resale median.
- The real test is not the launch price. It is the multiple over the area: did it hold through a weak market, through the handover year and through resale? I'd ask those three questions about any branded home.
In September, Khaleej Times reported Morgan's International Realty's H1 2026 figures for Dubai's branded residences: an average of AED 3,662 per sq ft against AED 2,354 for comparable non-branded homes. That is a 56% premium. The report's founder raised the question that matters: will those premiums last once the construction-period payment plans end? About 66% of the 64,744 branded units in the market are still being built, so for most of them nobody knows yet.
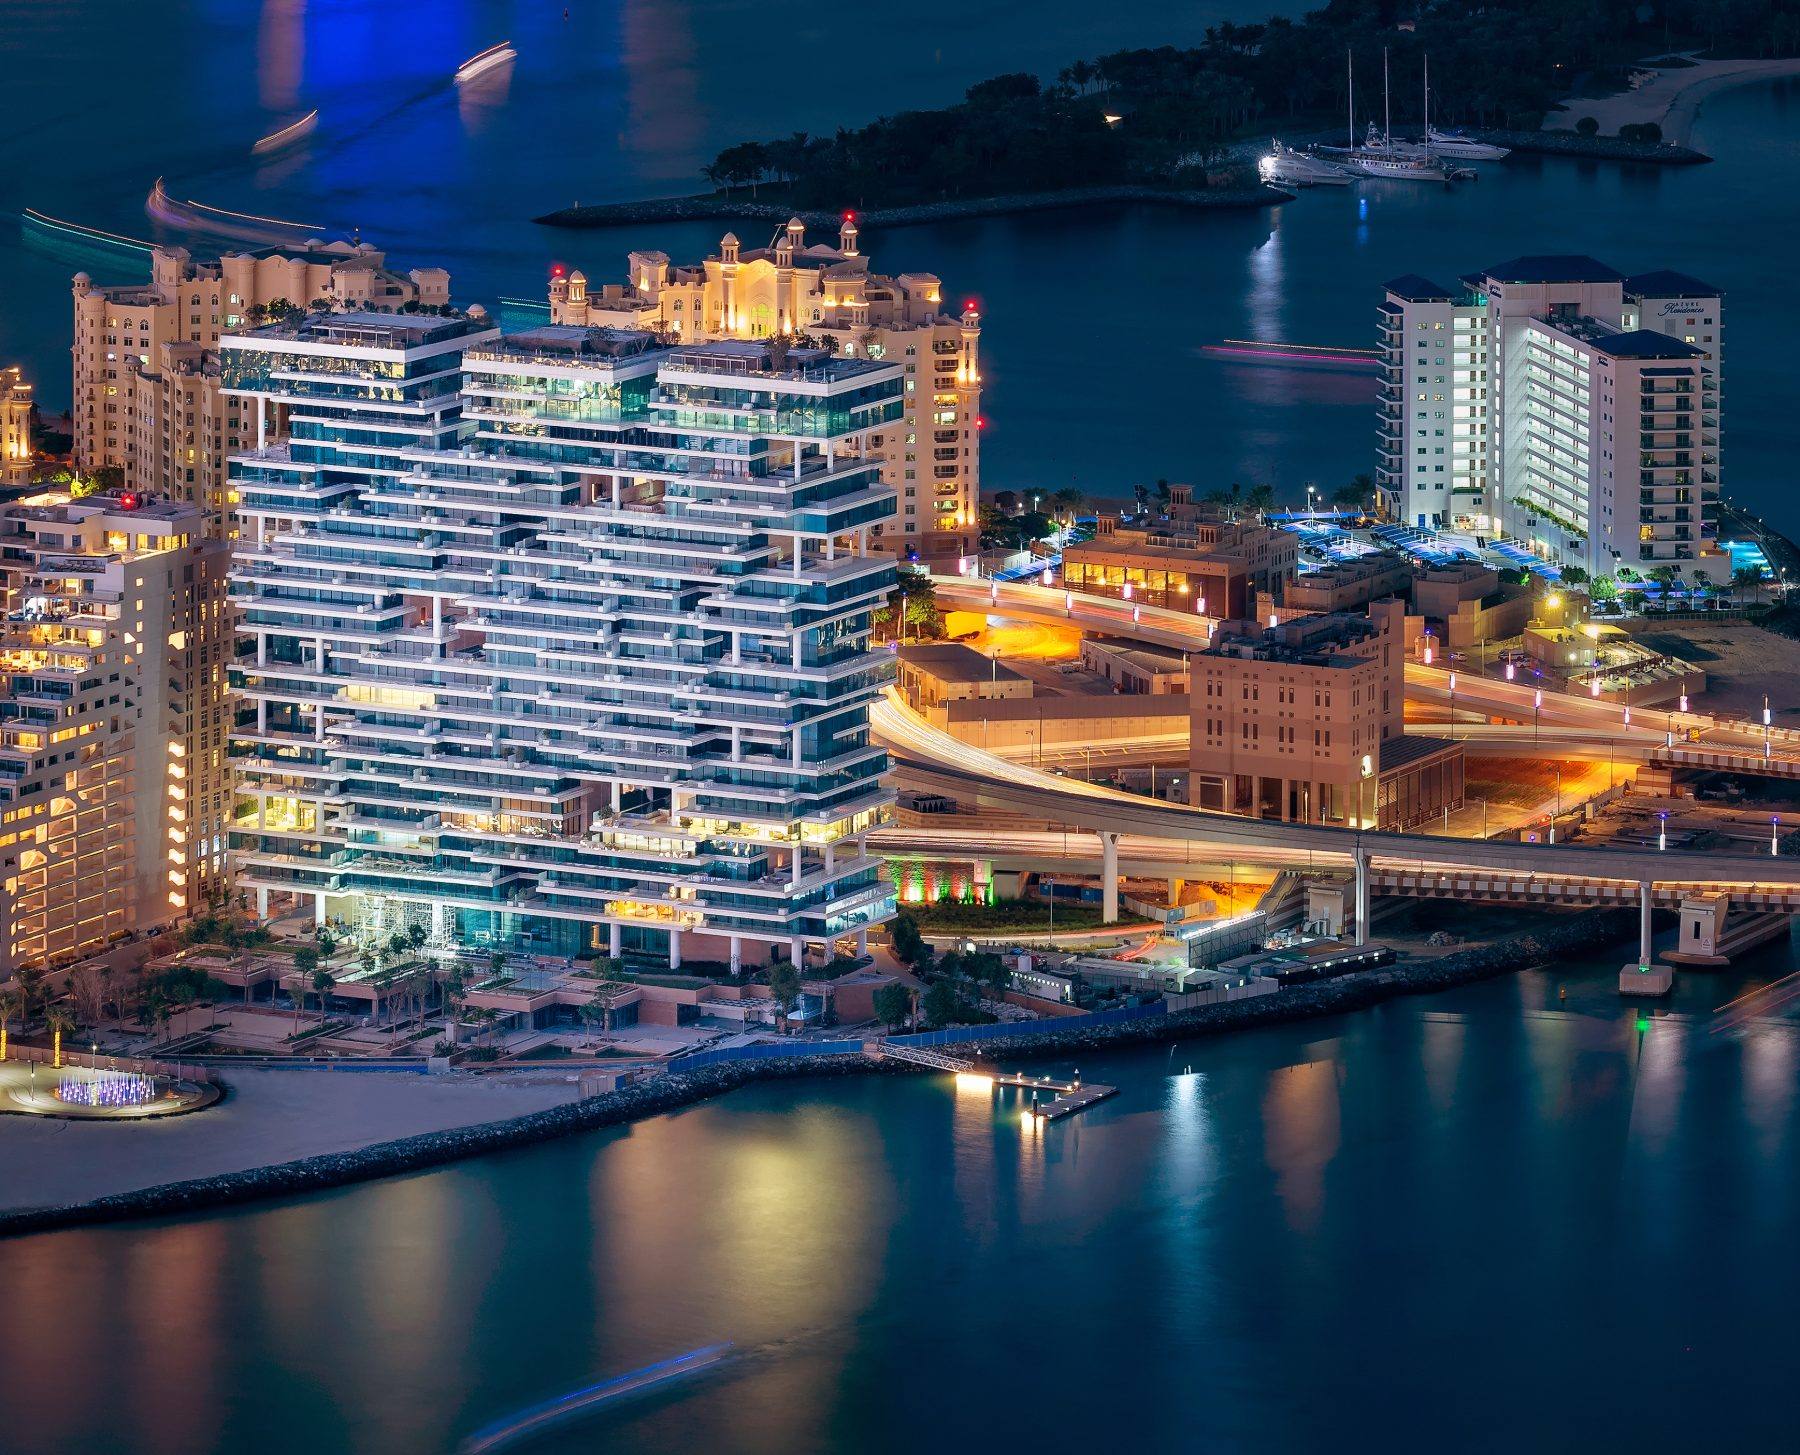
I'd rather answer with a building that has already been through it. One at Palm Jumeirah launched in 2015, handed over in 2021 and has been trading as a finished Dorchester Collection residence for five years.
The test that matters is the multiple, not the price
A rising price per sq ft tells you little on its own, because the whole Palm has risen too. The useful measure is how many times the area's resale median a branded home achieves, and whether that multiple holds when conditions change. (This is a different measure from Morgan's branded versus non-branded average, and I would not mix the two.)
| Year | One at Palm, AED/sq ft (sales) | Palm resale, AED/sq ft | Multiple |
|---|---|---|---|
| 2015 launch | 3,777 (18) | 1,629 | 2.3× |
| 2020 | 3,298 (5) | 1,057 | 3.1× |
| 2021 handover | 4,453 (63) | 1,434 | 3.1× |
| 2023 | 7,193 (20) | 2,314 | 3.1× |
| 2025 | 8,003 (15) | 2,877 | 2.8× |
| 2026 to date | 9,216 (3) | 2,890 | 3.2× |
What the three periods show
The quiet years. Between 2015 and 2020, the Palm resale median fell by about 35%. One at Palm's fell by about 13%, on very few sales: three to seven a year, too few to read as more than an indication. The premium did not shrink in the downturn. It widened, because the building held its value better than the island around it. For me, this is the most useful evidence a branded home can give.
The handover year. In 2021, 63 sales were registered, more than in the previous five years put together. That is the point where a premium usually cracks, because supply arrives all at once and some buyers want out. Here the multiple held at 3.1×.
Resale. Since then, the multiple has stayed between 2.7× and 3.1× in every full year, while volumes settled at 10 to 36 sales a year. Over the last twelve months the registered median was AED 9,140 per sq ft, 13.4% up on the year before, but on only four sales. On the Rental Index, six market leases point to a gross yield of about 5% over the same window. Past rents do not guarantee future income.
What earned it, as I see it: interiors by Elicyon and Super Potato, Dorchester Collection service from day one, and no new supply in the building. Owners who want to change a residence can work with OMNIYAT Atelier. I covered the full sales history in One at Palm: five years of sales.
What I would do
Before paying any branded premium, off-plan or ready, I would ask four questions:
- What is the multiple? Divide the building's median price per sq ft by the area's resale median. Ignore the launch price and the brochure.
- Did it hold in a weak year? A premium that only exists in a rising market is a payment plan, not a premium.
- What happened in the handover year? Find the number of sales and the multiple at the point when supply peaked.
- Who runs it once the developer has gone? The service, the operator and the after-care are what a buyer is still paying for in year five.
For a home still under construction, there are no answers yet to questions two and three. That is not a reason to walk away. It is a reason to buy from a developer and an operator who already have a completed building that passes them. If you are weighing resale against off-plan on the Palm, start there.
If you would like the same test run on a specific residence, send me a private enquiry.
Sources: Morgan's International Realty, Dubai Branded Residences Report H1 2026, as reported by Khaleej Times, 7 September 2026. Dubai Land Department registered sales via DXB Interact, pulled 11 November 2026: annual median price per sq ft and volume for One at Palm Jumeirah (all registered sales) and Palm Jumeirah (resale, apartments and villas); 2026 is year to date. Annual samples under 10 sales (2016–2020, 2026) are indicative only. Last-twelve-months figure on four sales. Rental yield: alihmoud.com Rental Index, Nov 2025 to Oct 2026, updated 3 November 2026. Multiples are rounded to one decimal. For information only; this is not investment advice and makes no forecast of future prices.